What proposed triple lock changes from 2030 mean for business owners
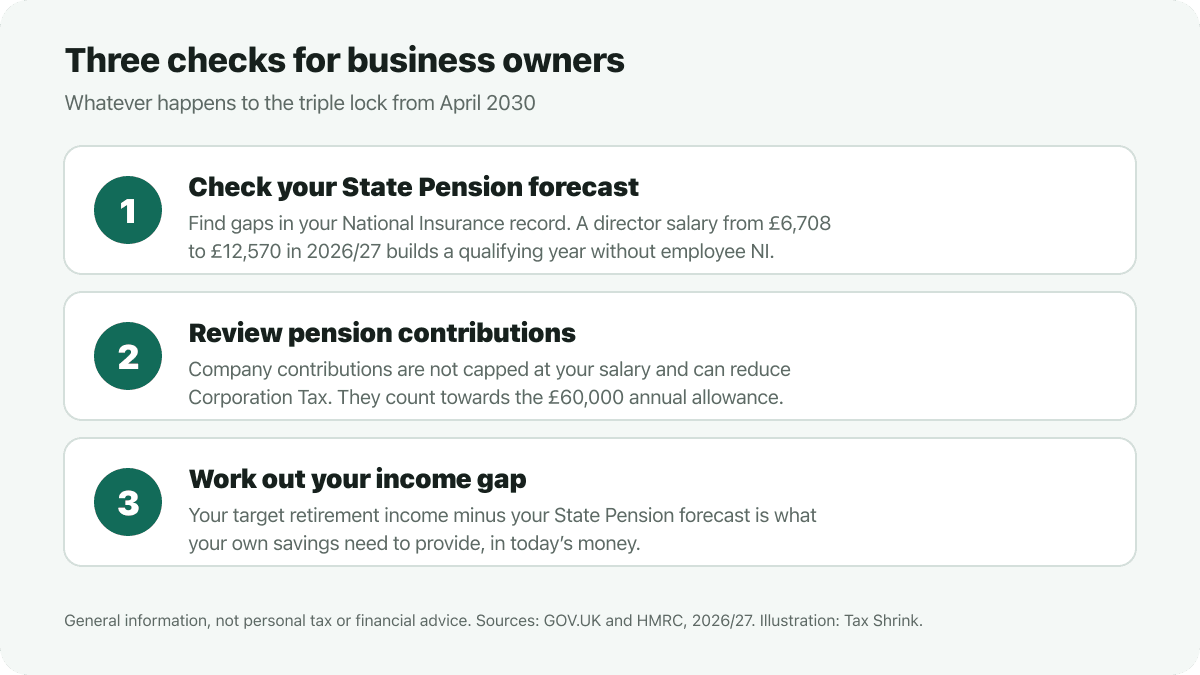
Proposed triple lock changes could slow State Pension increases from 2030. What UK directors and sole traders should check in their retirement planning.
Read articleTax changes rarely arrive in isolation. This blog explains the rules, announcements and practical questions that affect UK limited company owner-directors, using worked examples and links to the underlying sources.
You'll find timely analysis alongside clear guides to salary, dividends, National Insurance, Corporation Tax and regional Income Tax. Use them to understand the choices before you run the numbers; they provide general education and planning context, not advice tailored to you.
Proposed triple lock changes could slow State Pension increases from 2030. What UK directors and sole traders should check in their retirement planning.
Read article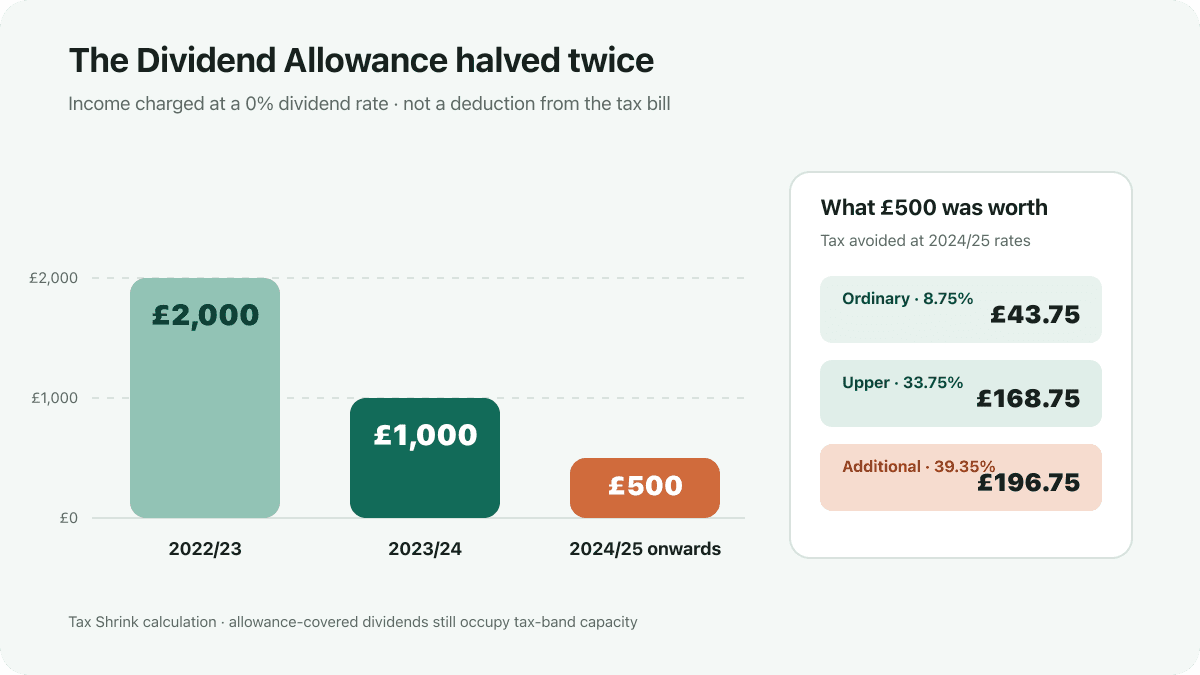
The £500 Dividend Allowance is income taxed at 0%, not £500 off your bill. It still uses dividend tax-band capacity.
Read article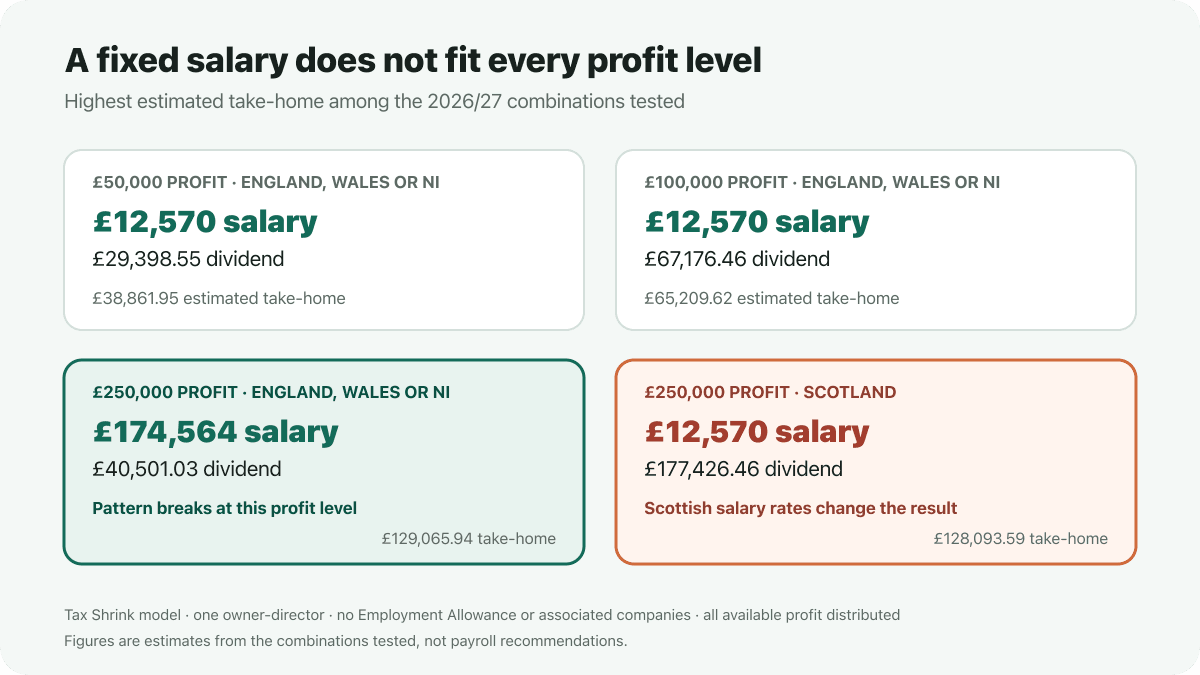
A £5,000 director salary can beat £12,570 in 2026/27. Compare five profit levels, both Income Tax regions and the effect of Employment Allowance.
Read article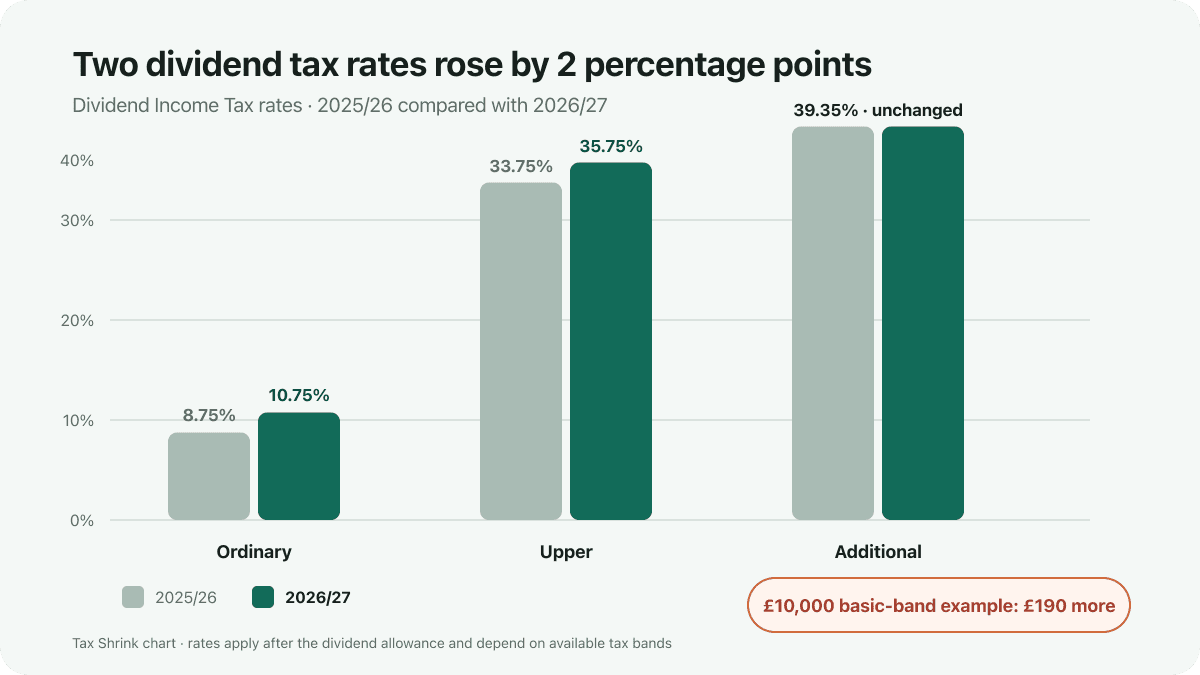
The 2026/27 director tax roundup: higher dividend rates, wider Scottish salary bands, unchanged NI and Corporation Tax, and the final BADR increase.
Read article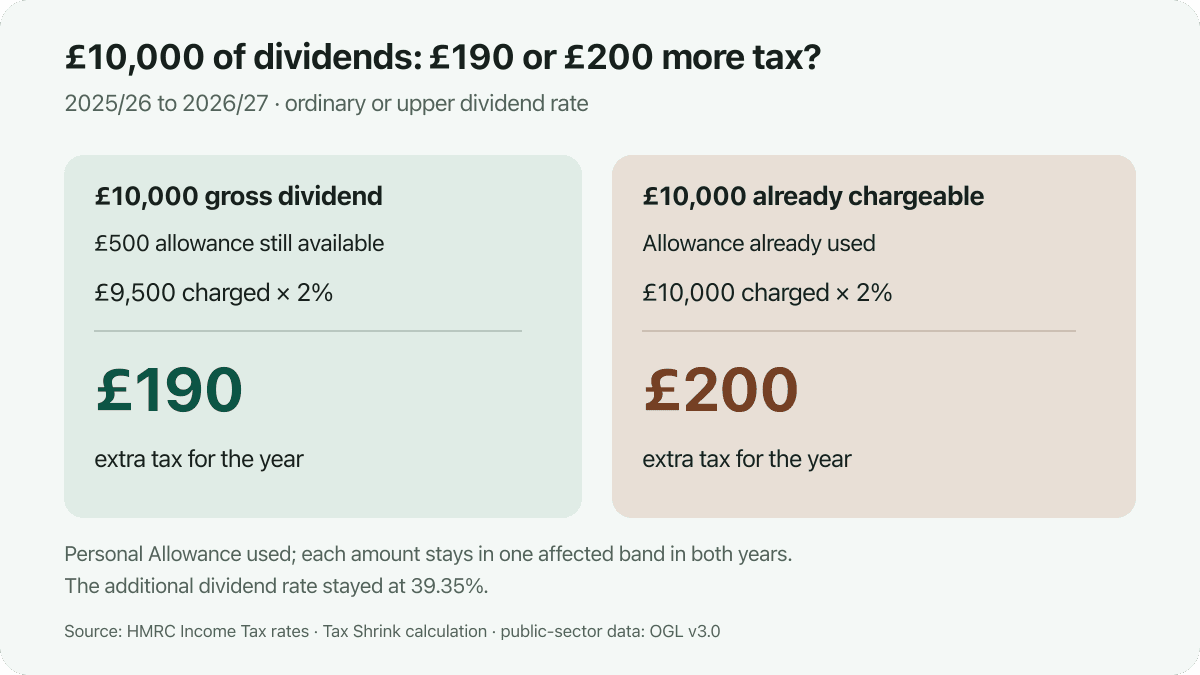
A £10,000 gross dividend can cost £190 more after the £500 allowance, while £10,000 already taxable can cost £200 more. See why the bases differ.
Read article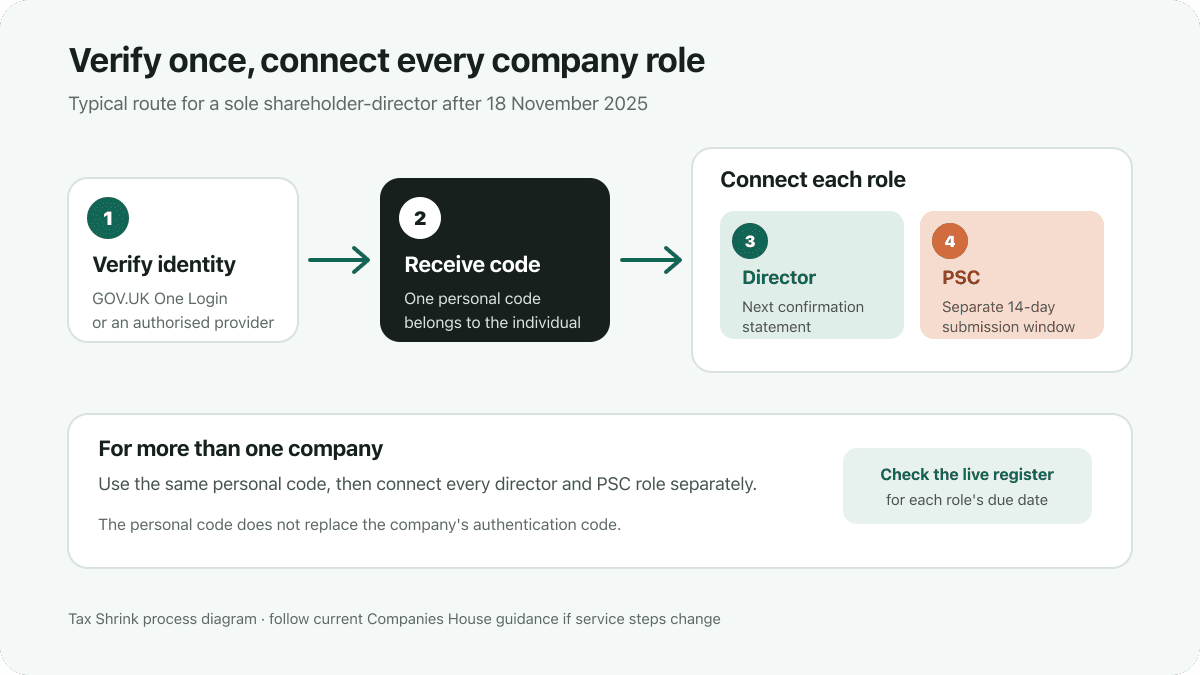
Companies House identity verification became mandatory on 18 November 2025. A sole director who is also a person with significant control must connect both roles.
Read article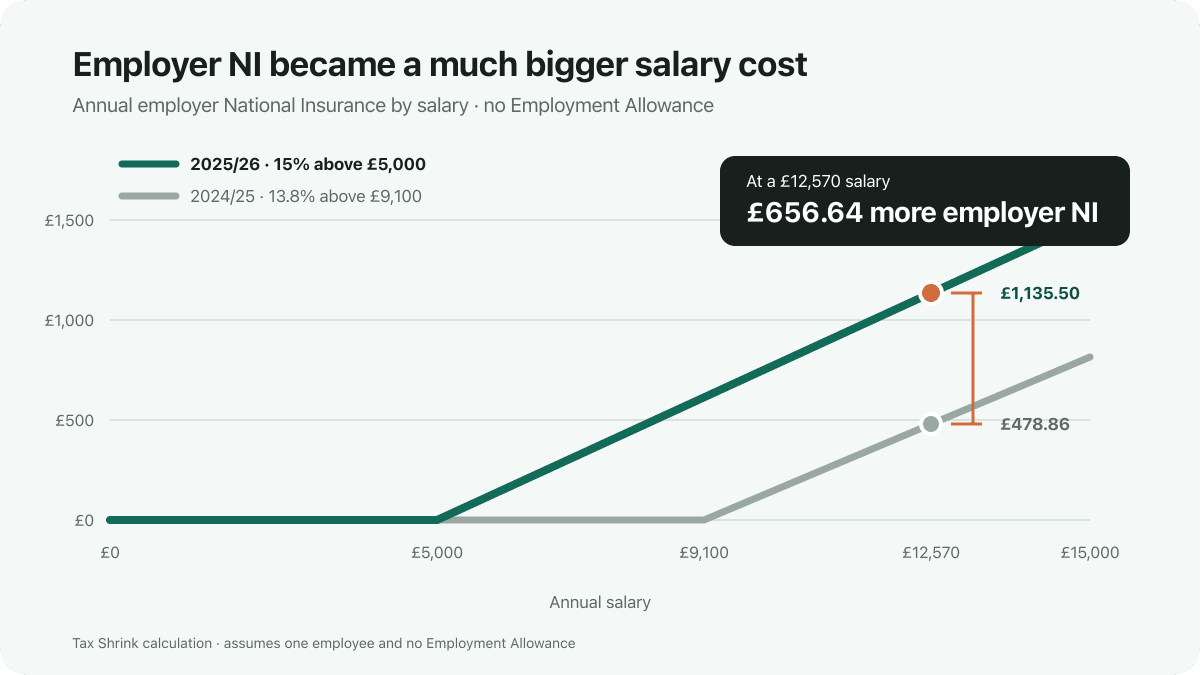
The 2025/26 director tax roundup: higher employer NI, modest Scottish salary-tax changes, unchanged dividend rates and new company obligations.
Read article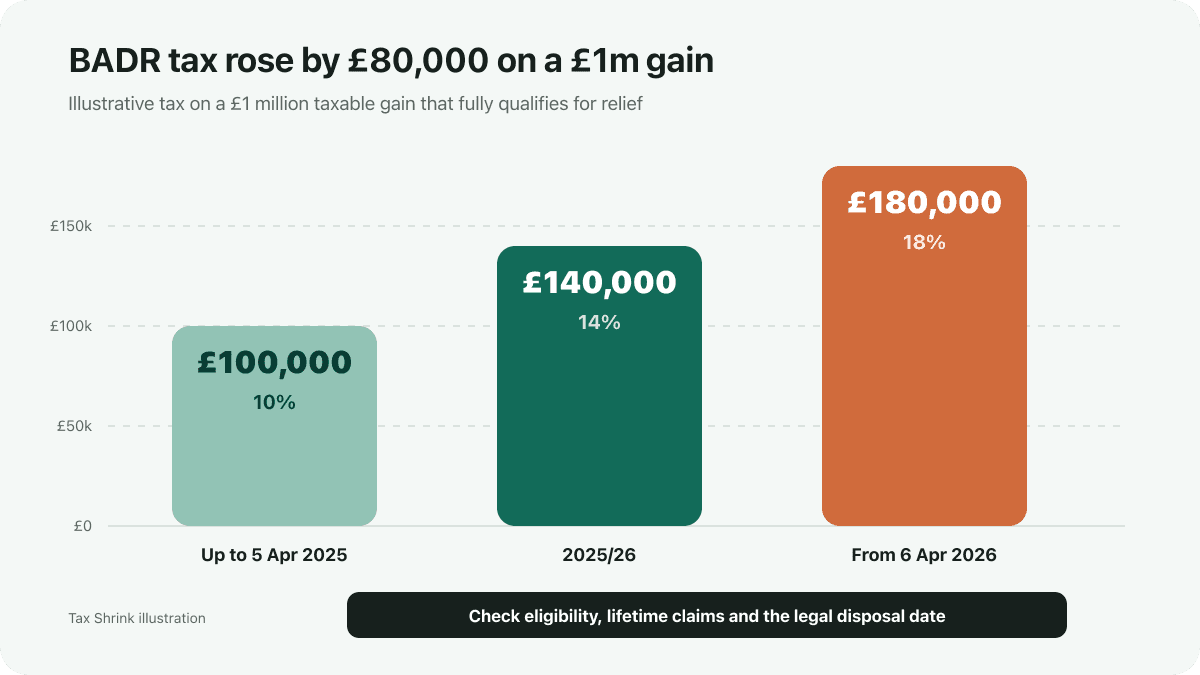
Business Asset Disposal Relief reached 18% in 2026. On a qualifying £1 million gain, that is £80,000 more tax than under the former 10% rate.
Read article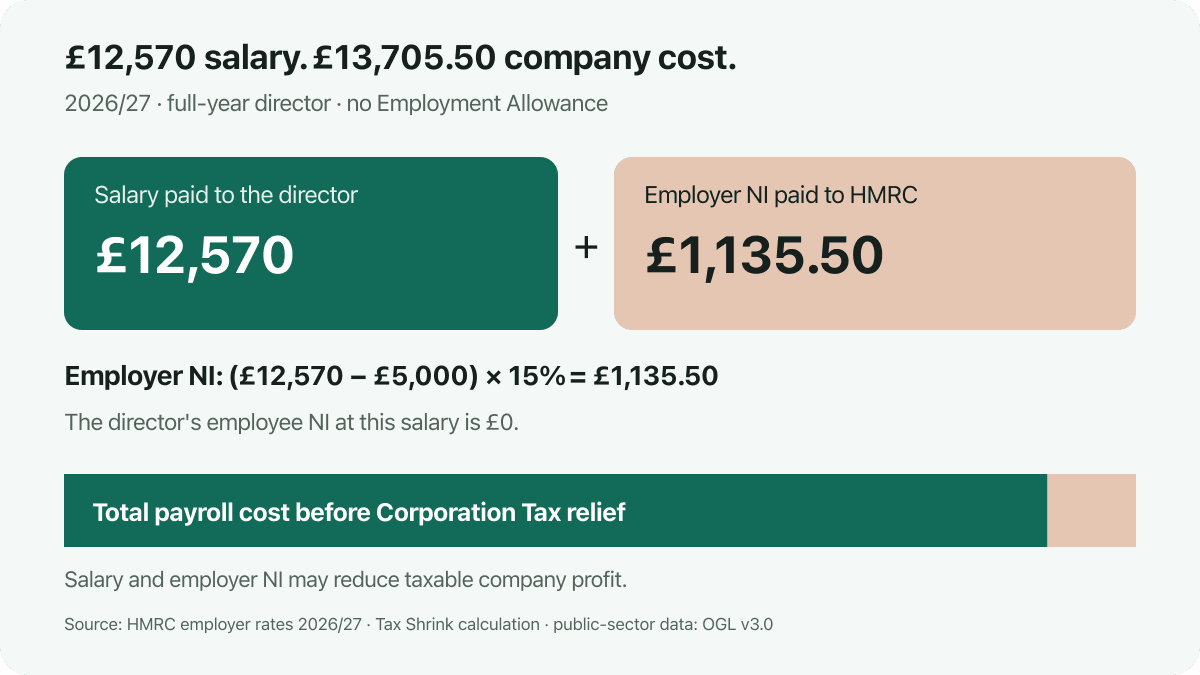
A £12,570 director salary creates £1,135.50 employer NI in 2026/27 without Employment Allowance. See the company cost and lower salary comparisons.
Read article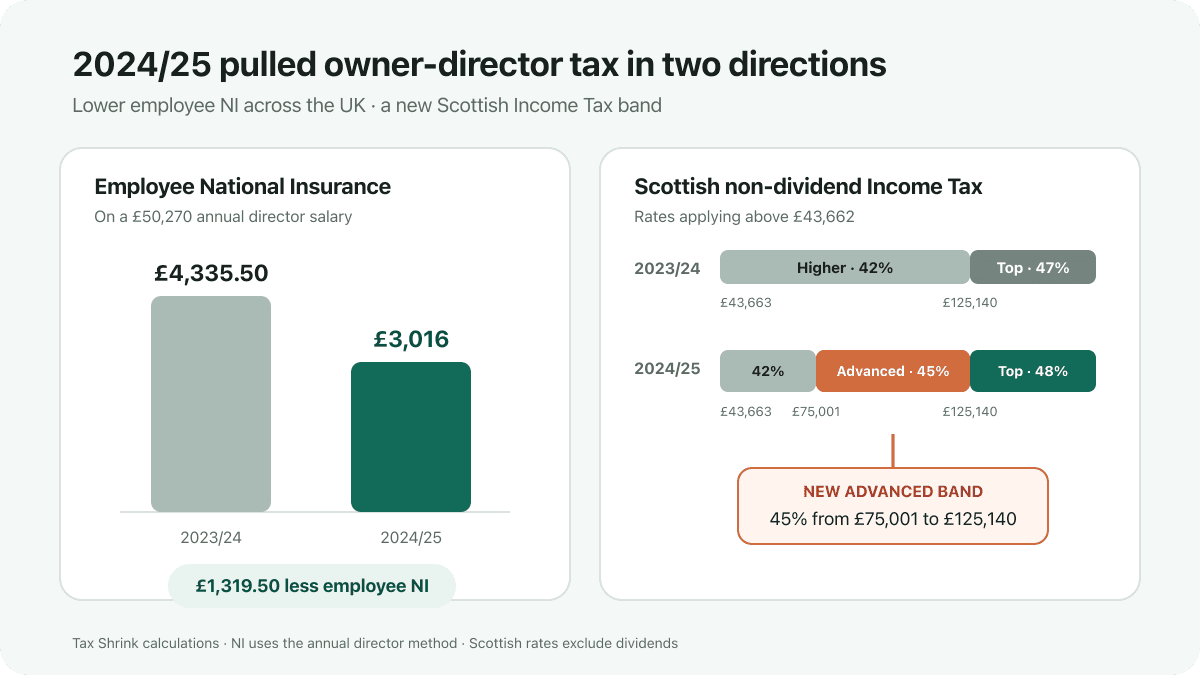
Employee NI fell to 8% in 2024/25, saving £1,319.50 at a £50,270 salary, while Scotland introduced a 45% Advanced rate.
Read article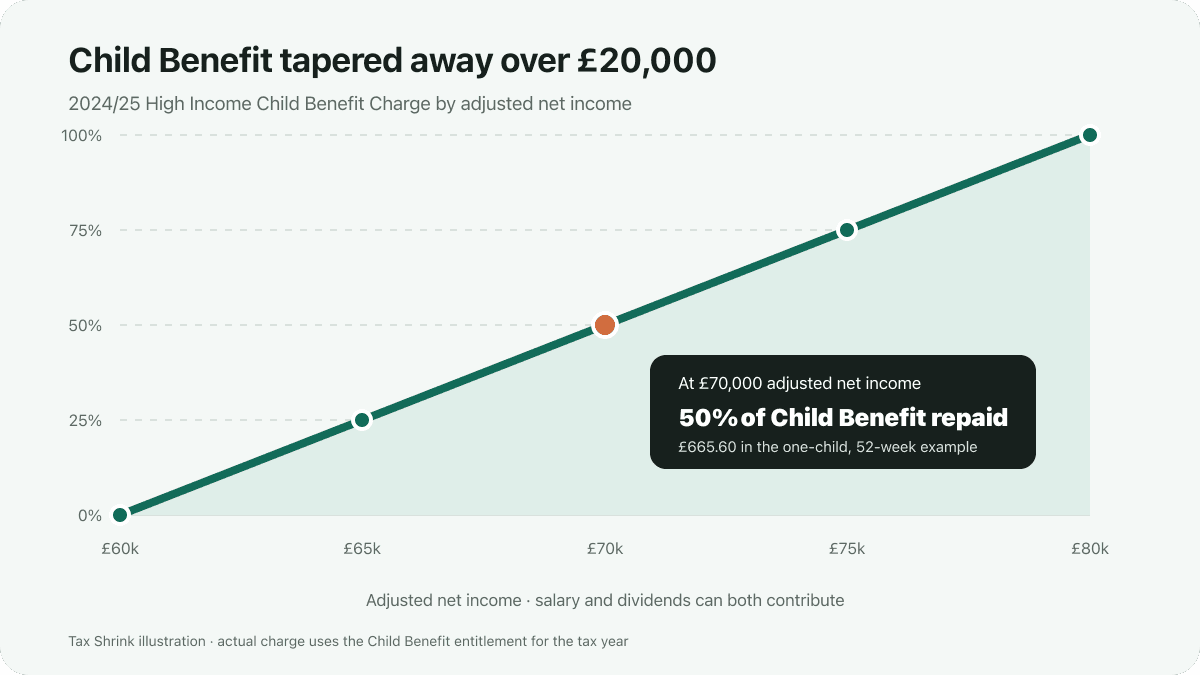
Salary and dividends both count towards adjusted net income. In 2026/27, Child Benefit is clawed back between £60,000 and £80,000.
Read article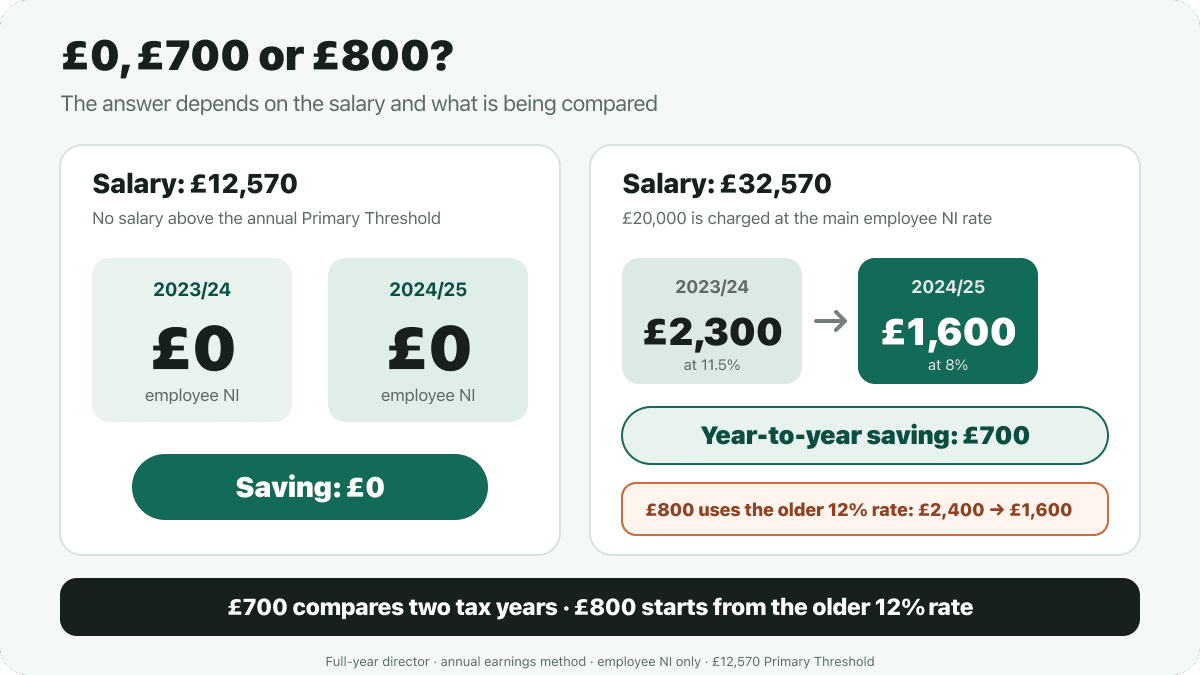
At a £12,570 director salary, the 2024 employee NI cut saved £0. At £32,570, the year-to-year saving was £700, not the quoted £800.
Read article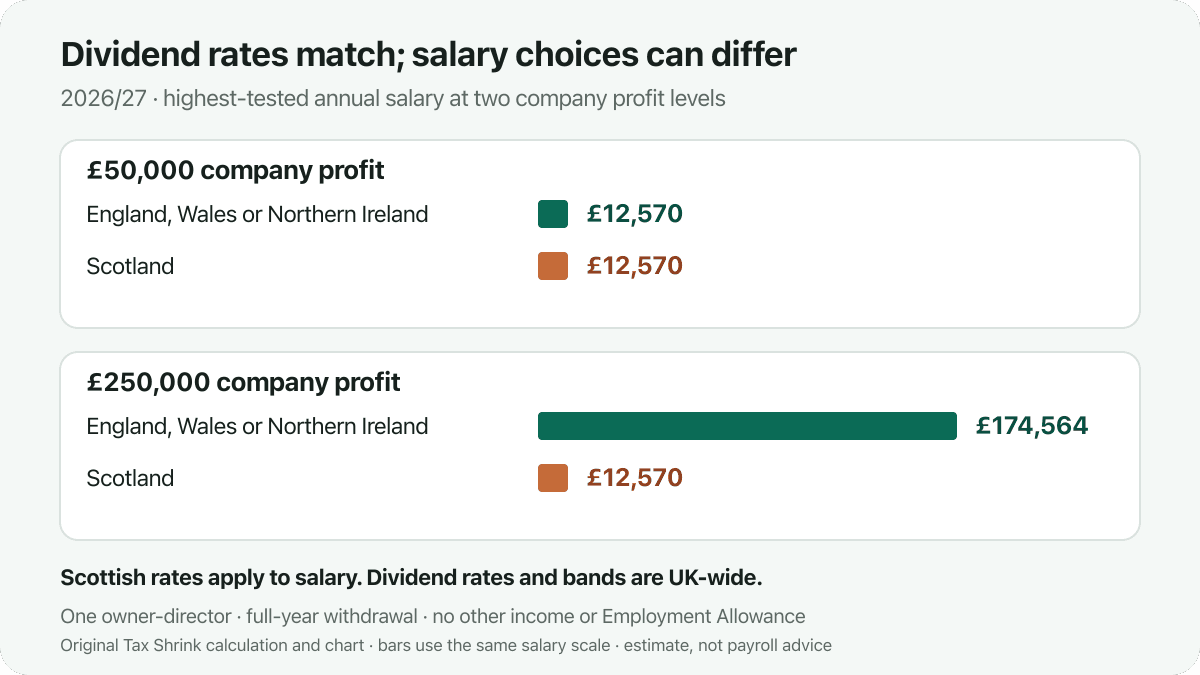
Dividends use UK-wide rates in 2026/27. Compare Scottish and English director pay examples to see when different salary tax changes the result.
Read article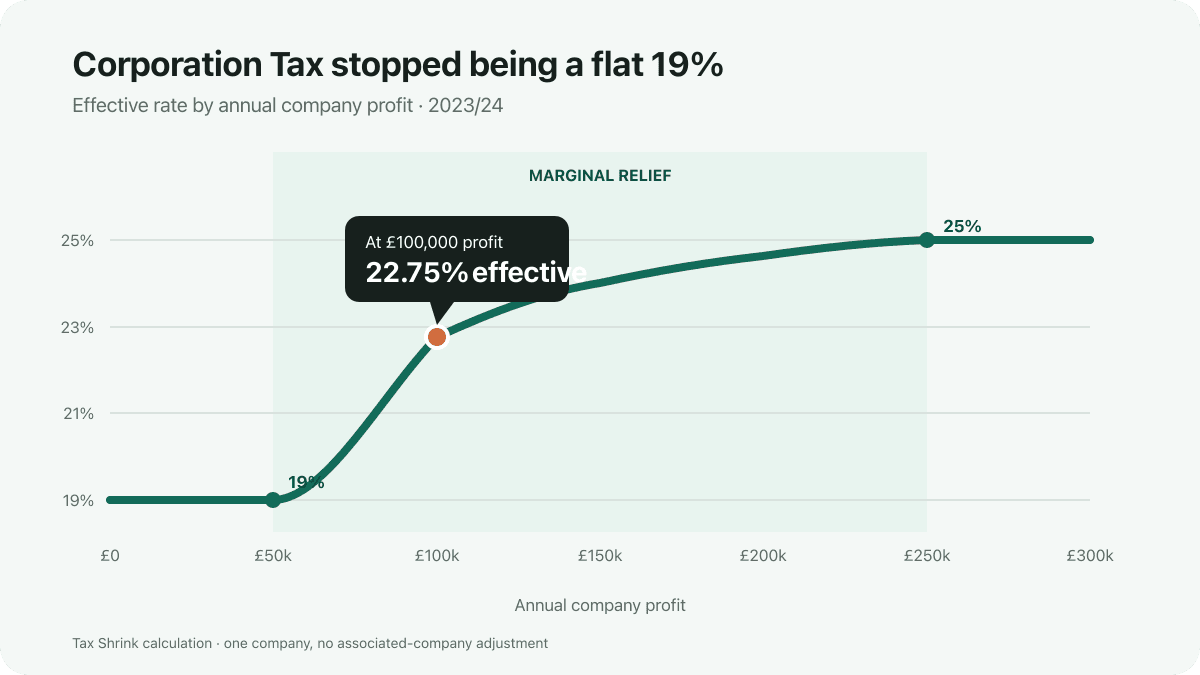
Corporation Tax on £100,000 of taxable profit became £22,750 from April 2023, before director pay. Associated companies can lower the thresholds.
Read article